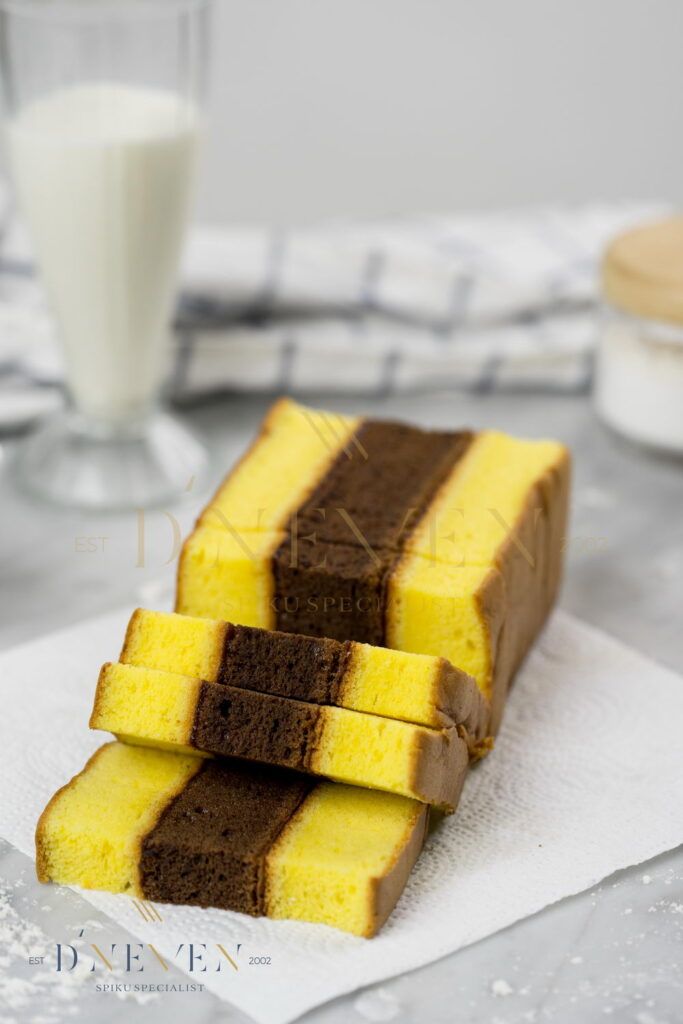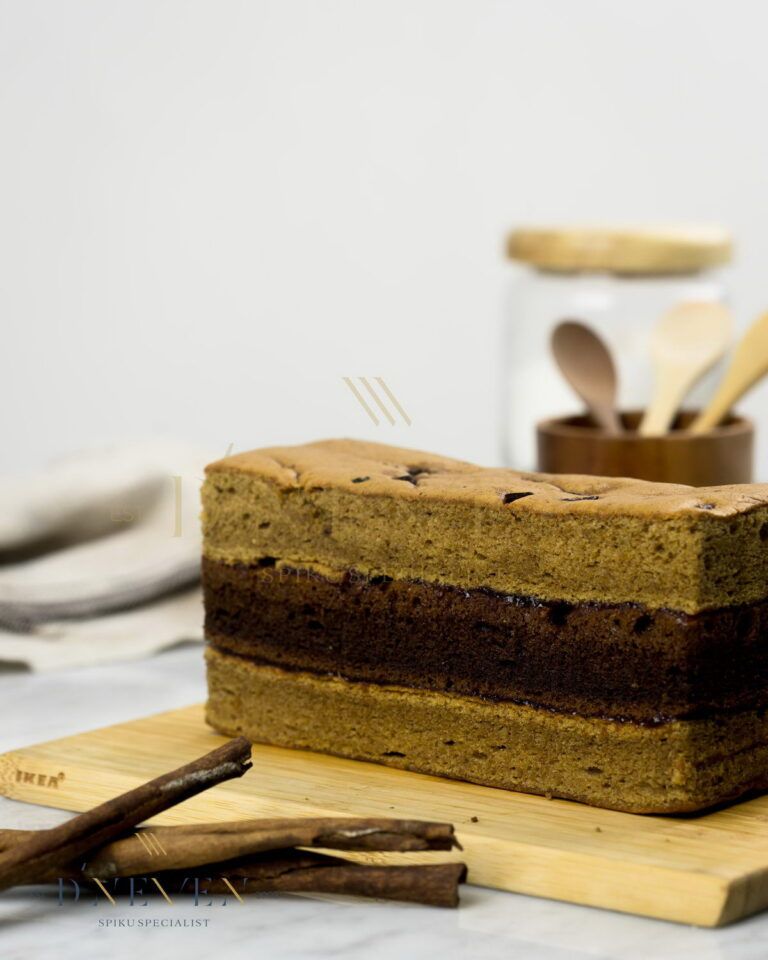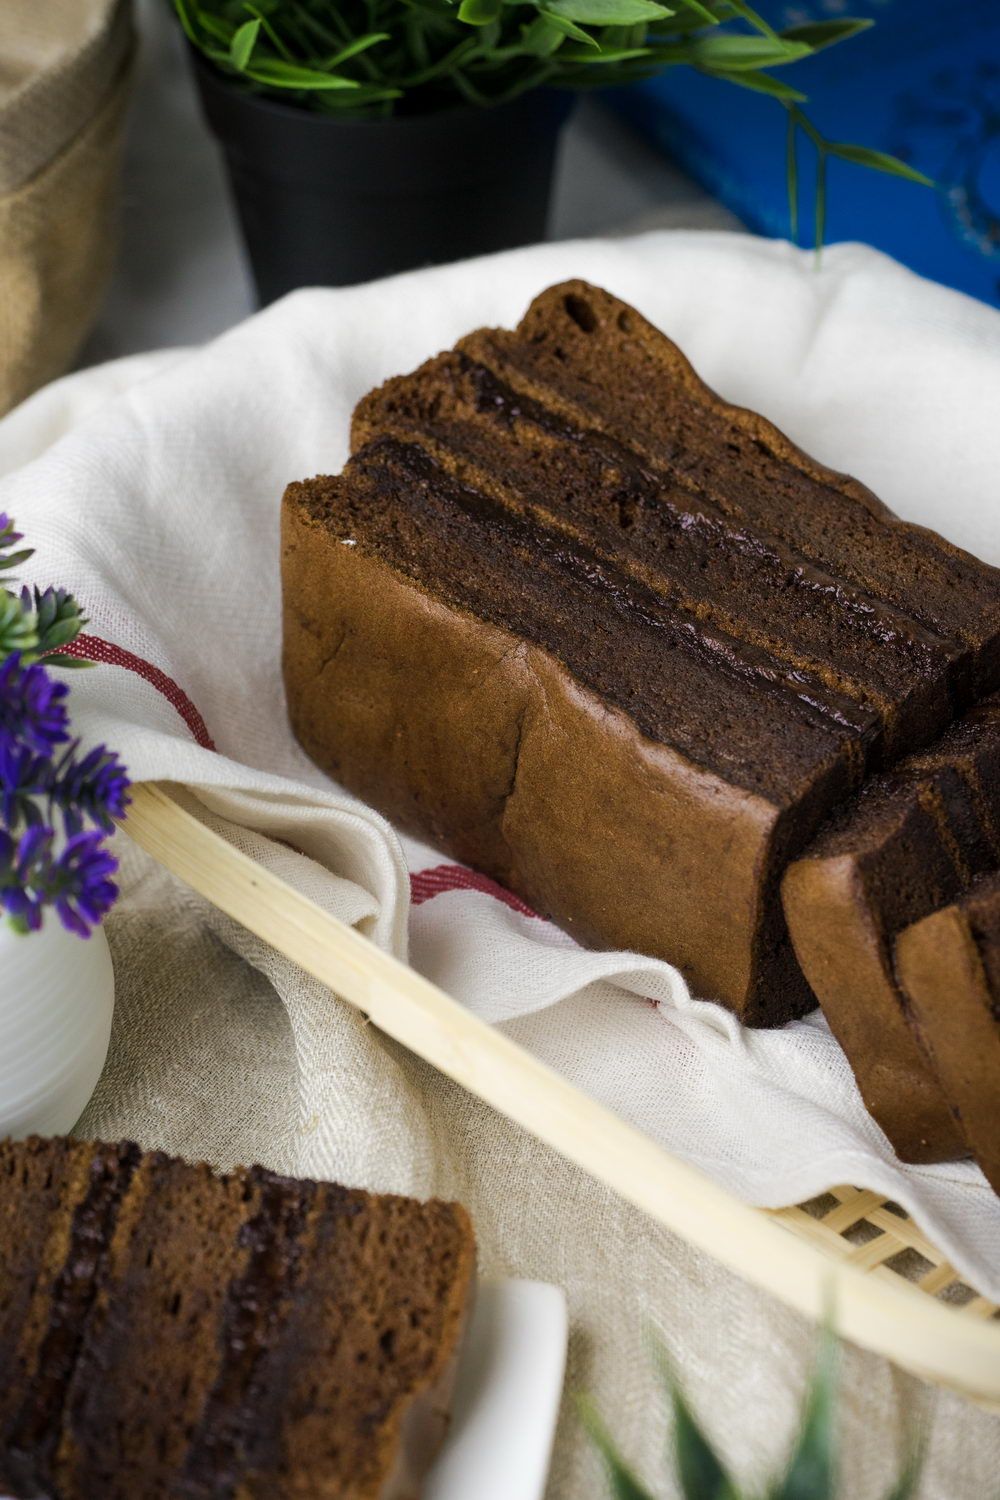
A gift budget is easier to discuss when its purpose is clear. You might be preparing spiku for one family, several business contacts, or groups with different requirements. Start with the recipients and the intention behind the gift, then connect those decisions to the funds available.
D’NEVEN SPIKU provides product information and official contact routes for discussing orders. Confirm prices, availability, and applicable arrangements in the ordering conversation. An internal budget helps you present a focused requirement before making the final choice.
Establish a reliable recipient count
Use a checked recipient list. Separate confirmed names from additions awaiting a decision. For gifts addressed to teams or families, decide whether one package is shared or each individual receives a separate package.
Counting errors can occur when several people compile the list. A contact might appear twice, while another group is identified only by its department name. Reconcile the list before dividing the budget so money is not allocated to recipients counted twice.
For a joint gift, identify who approves the final list. Constant changes make product comparisons and overall costs harder to read. Keep changes visible so subsequent decisions use the same recipient basis instead of different versions of the list.
Separate available funds from confirmed prices
Available funds are your or the organising team’s decision. Product prices and arrangement costs come from official confirmation. Record them in separate columns so an internal estimate is not mistaken for an accepted offer.
In an internal planning example, organisers set aside IDR 6,000,000 for 20 recipients. Dividing it equally leaves IDR 300,000 per recipient before other components are discussed. This figure describes the organisers’ budget capacity; product choices still need to match confirmed information.
If the team keeps IDR 500,000 unallocated, the remaining IDR 5,500,000 gives IDR 275,000 for each of 20 packages. Explain why those funds are reserved, such as an additional requirement being considered. Setting money aside does not make a possible cost compulsory or establish that a supplier charges it.
Identify the priorities to preserve
Choose two or three essential outcomes: accounting for every recipient, selecting a product suitable for sharing, or arranging handover on the required date. These priorities support decisions when the initial choice does not fit the available total.
For a family, sharing together might matter more than giving several small packages. For business contacts, organisers may need to agree consistent gifts for recipients with equivalent roles. One distribution pattern will not suit every activity.
Use the gift selection guide to discuss the recipient and occasion. Evaluate sizes and flavours using available product information, then confirm the choice for your requirement. Avoid adding assumptions about servings or services that have not been explained.
Request costs on a consistent basis
When asking for confirmation, send a list identifying products, chosen sizes, quantities, required date, and the handover arrangement you want to discuss. A comparison is useful only when the options use the same quantities and requirements.
Record components actually confirmed. If you need an additional arrangement, ask whether it is available and how its cost is calculated. Do not assume that a gift message, packaging change, or particular delivery is automatically included.
Give figures a status: awaiting confirmation, confirmed on a specified date, or needing revision after a change. A previously correct amount may need checking again when quantities or arrangements change. A summary lets organisers read the current decision rather than relying on an older conversation.
Change one decision at a time
If the total does not fit, avoid changing products, recipient numbers, and dates simultaneously. Choose one element to discuss and request an updated summary. This helps identify which change brings the plan within the available budget.
Do not reduce the recipient list without approval from its owner. If a shared gift for a team is being considered, check that this suits the purpose. Changing the format affects the recipients’ experience, so it needs a clear reason rather than being treated as an invisible accounting adjustment.
Avoid promising organisers a discount or particular term before confirmation. State the requirement and available funds honestly. An official conversation can explain available choices without leading the group to assume its initial request will necessarily be accepted.
Retain the final approval and change owner
The final summary contains recipient quantities, approved products, the confirmed total, handover arrangements, and the approver. Keep unanswered questions visible if any remain; the plan is not yet complete for its next step.
If another recipient is added after approval, identify who reviews the change and communicates it. Unallocated funds are not automatically available for anyone to spend. Decisions still follow the organising team’s agreement.
For a group order, begin with the D’NEVEN SPIKU corporate gifting guide. A clear budget does more than seek the lowest number. It protects the purpose of giving, accounts for recipients, and supports decisions the organisers can approve and carry out together.